
The recently announced First Time Buyer ISA is due to launch in April 2029, but LISAs remain available now and they can still support a Shared Ownership purchase.
There is also an immediate change for buyers considering homes above the £450,000 LISA limit. In this guide, we explain what is changing, what it means for Shared Ownership buyers and how a LISA could help with your deposit.
What is changing for first-time buyers?
The government has confirmed that the First Time Buyer ISA is going to replace the LISA for new savers from April 2029.
However, if you have already opened a LISA, you'll still be able to contribute to it and use the account under the current rule.
Under the new announced plan, first-time buyers aged 18 or over will be able to save up to £4,000 a year like the LISA, with no upper age limit.
A 25% government bonus will be calculated on the final balance, including interest or investment growth, up to a maximum bonus of £20,000. Unlike a LISA, the bonus will be paid when buying a qualifying home rather than as you save.
The new account will have no withdrawal charge: though money taken out for other purposes will not receive a purchase bonus. The £450,000 property price cap will remain, and the account is for first-home purchases, not retirement saving.
For Shared Ownership buyers the key point is timing, as the new ISA is not available yet. A LISA can still help eligible buyers saving for a home now.
Check the final First Time Buyer ISA rules for Shared Ownership before relying on it for a future purchase. You can also keep an eye on the government’s First Time Buyer ISA announcement for further updates.
What is a Lifetime ISA?
A Lifetime ISA is a savings or investment account designed to help people save for their first home or later life.
You can open one if you are aged 18 or over but under 40, and you can continue paying into it until you turn 50.
You can contribute up to £4,000 each tax year.
The government then adds a 25% bonus to your contributions.
This means if you save the full £4,000 per year, you'll get an extra £1,000, leaving you with £5,000 towards an eligible home purchase.
Lifetime ISA vs the new First Time Buyer ISA Table
Feature | Lifetime ISA (LISA) | New First Time Buyer ISA |
|---|---|---|
Availability | Available now to eligible savers. | Due to launch in April 2029, replacing the LISA for new savers. |
Age rules | Open aged 18–39; contribute until age 50. | Open from age 18, with no upper age limit. |
Annual contribution limit | £4,000 per tax year. | £4,000 per tax year. |
Government bonus | 25% of contributions, up to £1,000 each tax year, added as you save. Maximum bonus of £33,000. | 25% of the final balance, including interest or investment growth, paid when buying a qualifying home; maximum total bonus of £20,000. |
Property price cap for keeping the bonus | £450,000. (For Shared Ownership, this is the full market value, not the share price.) | £450,000. |
Withdrawals for a first home above £450,000 | 20% is deducted from your withdrawal to take back the government bonus. | No withdrawal charge, but no government purchase bonus above the cap. |
Other withdrawals | Usually a 25% charge before age 60 unless an exemption applies. | No withdrawal charge but money withdrawn for other purposes receives no purchase bonus. |
Retirement saving | Can also be used for retirement, with charge-free access from age 60. | Designed for buying a first home, not retirement saving. |
Existing LISA holders | Can continue contributing to and using their accounts under the current rules after the new ISA launches. | Does not require existing LISA holders to close their accounts.The First Time Buyer ISA is not available yet. This comparison reflects the announced rules as of 5 November 2026. |
The First Time Buyer ISA is not available yet. This comparison reflects the announced rules as of 5 November 2026.
Expert Advice on LISA usage for Shared Ownership purchases
To get a mortgage adviser's perspective, we asked Anthony Hall, a Director from Censeo Financial, to share his insights on using a Lisa for a Shared Ownership purchase:
1. What do you wish more first-time buyers knew about using a LISA for Shared Ownership?
One of the biggest things I wish more first-time buyers understood is that a Lifetime ISA can actually be used towards a Shared Ownership purchase, and knew it can make a real difference when saving for a deposit.
With Shared Ownership, buyers are purchasing a percentage of the property, so the deposit required is typically much lower than buying outright. The LISA's 25% government bonus, worth up to £1,000 a year, can therefore be particularly valuable.
2. At what point should a buyer tell their mortgage adviser that they have a LISA?
Ideally, at the very first conversation, before they start viewing properties or commit to a reservation.
A mortgage adviser needs to understand where the deposit is coming from, how much is available and whether those funds can be used for the intended purchase.
For a LISA, there are some additional considerations. The account must have been funded for at least 12 months before it can be used towards a qualifying first-home purchase without a withdrawal charge.
It's also important that the solicitor is aware early in the process, as LISA funds have to be withdrawn through the conveyancer.
For Shared Ownership in particular, identifying this at the outset allows the adviser to check the property's full market value, establish whether the LISA qualifies and ensure the buyer has sufficient funds available for the purchase.
3. What mistakes or misconceptions do you commonly see around LISAs and deposits?
The biggest misconception is that having enough money for the deposit automatically means someone is financially ready to purchase.
With Shared Ownership, we need to consider the whole picture. That includes the mortgage repayment, rent on the remaining share, service charges and other household commitments.
Someone may have built up an excellent deposit using their LISA but still find that the monthly costs of a particular property are unaffordable.
Another misconception is that the LISA limit relates to the share being purchased rather than the full property value. The £450,000 LISA property price limit applies to the full market value of the property, not just the share being purchased.
For example, someone purchasing a 25% share of a £500,000 property would be buying a share worth £125,000, but the property would still exceed the LISA limit.
Understanding this before starting a property search can prevent disappointment later.
Buyers can also overlook the 12-month qualifying period or assume their LISA savings can be withdrawn freely to cover expenses such as legal fees.
The recent reduction in the withdrawal charge to 20% for qualifying first-home purchases above £450,000 is welcome, as it means buyers can access their savings without losing part of their original contributions purely because the property exceeds the cap. However, they would still lose the benefit of the government bonus.
My advice is always to look beyond the deposit and establish what is genuinely affordable before committing to a property.
4. If someone has a LISA today, should the announcement of the new First Time Buyer ISA change what they do?
Not necessarily. I certainly wouldn't encourage someone to stop saving simply because a new product has been announced.
The new First Time Buyer ISA isn't due to launch until April 2029, and existing LISA holders will be able to continue using and contributing to their accounts under the existing rules.
The new product will retain the 25% government bonus, but that bonus will be paid when the money is used for a qualifying purchase rather than being added to savings along the way. It will also remove the withdrawal penalty associated with the existing LISA structure.
For someone already saving towards a property within the next year or two, their existing LISA could remain a very effective option.
The important thing is to understand the rules, particularly the £450,000 property limit, and whether those rules align with the type of home they are likely to purchase.
I would encourage buyers to review their plans rather than make changes based purely on the announcement of a future savings product.
5. What should someone starting to save for their first home be thinking about now?
My advice would be to start by understanding what you can realistically afford to buy, rather than concentrating solely on how much deposit you need.
Shared Ownership is a good example of why this matters. A buyer might only need a relatively modest deposit to purchase a share of a property, but their income and monthly expenditure will ultimately determine whether that purchase is affordable.
I would encourage anyone starting their savings journey to consider three things: how much they can save consistently, when they realistically hope to purchase, and what type of property they are likely to afford.
For those eligible for a LISA, the 25% government bonus can be extremely beneficial, particularly if they are several years away from buying. Starting early also helps meet the 12-month qualifying requirement.
They should also keep some savings accessible for legal fees, moving costs and unexpected expenses, rather than committing every available pound towards the deposit.
Ultimately, the aim shouldn't just be to save enough to buy a home, but to buy a home you can afford.
How could a LISA help with your deposit?
The government bonus adds to the money you have saved yourself, reducing the time it takes to build up your deposit. The following examples show how this could work at Lombard Square, where 14 homes fall within the £450,000 full market value cap.
One-bedroom example at Lombard Square
For a one-bedroom home with a full market value of £305,000, a 25% share would cost £76,250.
If the required deposit were 10% of that share, the deposit would be £7,625.
To build a £7,625 LISA pot through contributions and the government bonus alone, you would need to save £6,100 of your own money. A 25% government bonus would add £1,525, taking the total to £7,625. If you were able to maximise your LISA contributions across two tax years, you could build the required £7,625 in as little as 12 months.

Two-bedroom example at Lombard Square
For a two-bedroom home with a full market value of £405,000, a 25% share would cost £101,250.
A 10% deposit on that share would be £10,125.
In this example saving £8,100 into a LISA would attract a £2,025 government bonus, producing a total of £10,125.
As the annual LISA contribution limit is £4,000, building this amount would require saving over more than one tax year.
Financial information provided is estimated and should be used for guidance only. Speak to an Independent Mortgage Advisor for more details about the costs involved with buying a home.

Peabody homes at or below the £450,000 LISA limit
These examples are illustrative. The share you can buy, the deposit required and the mortgage available will depend on your circumstances, the property and affordability checks.
Other costs involved in Share Ownership, including legal fees, mortgage payments, rent and service charges, should also be included in your budget.
Other Peabody developments shown with homes at or below the £450,000 LISA limit include:
Lombard Square – from £310,000
West Ham Village – from £395,000
Dagenham Green – from £270,000
Frankham Walk – from £415,000
Southmere – from £332,500
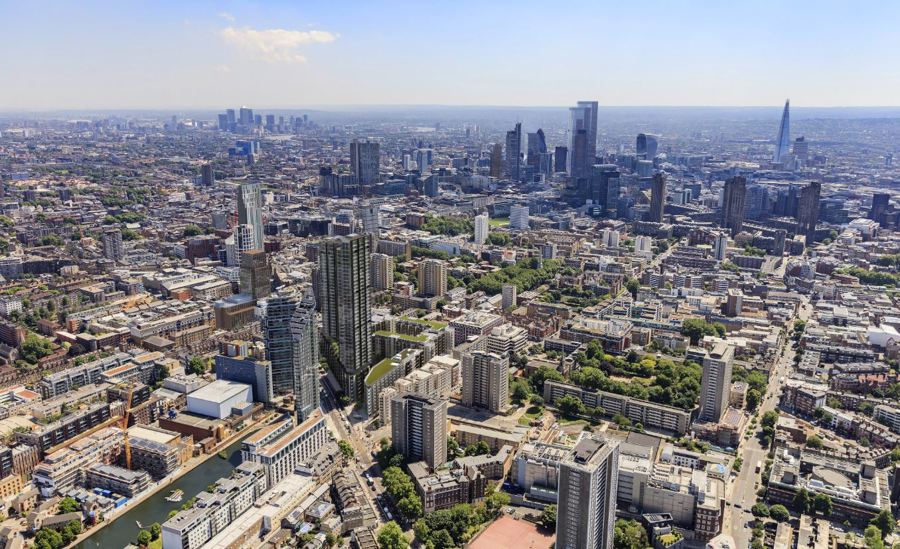
Deptford Edge – from £395,000
Fish Island Point – from £450,000
KEWB – from £427,500
The Verdean – from £403,000
Heather Fields – from £365,000
Where can I get a Lifetime ISA?
Several providers in the UK offer Lifetime ISAs. You can choose between a cash savings account, which earns interest, and a Stocks and Shares Lifetime ISA, which lets you invest your money. Here are some UK providers to consider:
Moneybox – Moneybox offers both Cash and Stocks and Shares Lifetime ISAs. It is an option for savers who prefer managing their account through an app, with the flexibility to save in cash or invest.
Skipton Building Society – Skipton offers a Cash Lifetime ISA for people saving towards their first home or retirement. It can suit those who prefer earning interest on their savings rather than investing.
The Nottingham Building Society – The Nottingham offers an online Cash Lifetime ISA.
Hargreaves Lansdown – Hargreaves Lansdown provides a Stocks and Shares Lifetime ISA, with options to select your own investments or choose ready-made portfolios.
Frequently asked questions about LISAs
Yes. A LISA can be used to buy a Shared Ownership home, provided both the LISA rules and the Shared Ownership eligibility requirements are met.
With Shared Ownership, you buy an initial share of a home and pay rent on the remaining share.
You can fund the share you buy with a mortgage and provide a deposit based on that share, instead of the home’s full market value. This can make the upfront deposit more achievable than buying the same home outright.
An important point to bear in mind is that the LISA property price limit is based on the home’s full market value, not the price of the share you are buying. This cap determines if you can keep the government bonus; the reduced-charge option above it is explained below.
To make a charge-free withdrawal for a first-home purchase, the full property price must be £450,000 or less.
Starting from October 29th 2026, the LISA withdrawal charge for first-home purchases over £450,000 fell from 25% to 20%.
The reduced charge removes the extra deduction from your own savings, although investment losses can still mean you receive less than you paid in. It applies only to eligible withdrawals made on or after 29 October 2026. Other unauthorised withdrawals still incur a 25% charge.
For Shared Ownership, check the home’s full market value (not just your share price).
If it exceeds £450,000, ask your LISA provider and conveyancer to confirm the reduced charge route before withdrawing. You can read HMRC’s guidance on the reduced withdrawal charge for more information.
To use a LISA for a charge-free first-home purchase, you will generally need to meet the following conditions:
You must be a first-time buyer.
The home’s full purchase price must be £450,000 or less.
At least 12 months must have passed since your first payment into the LISA.
You must be buying the home with a mortgage and intend to live in it as your main residence.
Your LISA provider will normally send the money directly to the solicitor or conveyancer handling your purchase.
Other unauthorised withdrawals before age 60 will usually attract a 25% charge. The reduced 20% charge applies only to otherwise qualifying first-home purchases above £450,000. It's therefore worth checking the latest rules and speaking to your LISA provider before committing funds.
If you already have a LISA, mention it early when making an enquiry and during your affordability assessment.
This gives your sales adviser, mortgage adviser and conveyancer time to confirm that the home and purchase process meet the relevant conditions.
You should also check the full market value of any Shared Ownership home you are considering. A low initial share price does not automatically make the property eligible for LISA use; be sure its full value is £450,000 or less to keep the government bonus.
Shared Ownership can significantly reduce the amount you need to save for a deposit, whilst the LISA adds a 25% bonus onto your savings. Combined, they can accelerate you onto the property ladder.
If you are planning to buy before April 2029, the forthcoming First Time Buyer ISA will not be available for your purchase. Consider the LISA rules alongside your buying timetable, including the 12-month wait from your first payment.
Before applying, review the latest LISA and Shared Ownership criteria, consider all upfront and monthly costs, and seek independent financial advice where appropriate.
You can then explore Shared Ownership homes with a clearer understanding of how your savings could support your purchase.
The limit is based on the home’s full market value, not the price of the share you are buying. The full value must be £450,000 or less.
At least 12 months must have passed since your first payment into the LISA before you can make a charge-free withdrawal towards your first home.